Individual Health Insurance vs Family Floater Which is Better?
15 October,2026
Updated:15 October,2026
0 min read

share


Copied
 35
This blog shares a detailed comparison of individual and family floater insurance, so you can choose the right plan.
People have now realised the real importance of health insurance in today’s economy, but many face a common roadblock when buying one: confusion about whether to choose individual or family floater insurance.
Although both are great options, they differ significantly in policy structure. So, we’ve shared an insightful analysis of individual vs family floater plans in this blog to help you choose the right plan for yourself and your family.
What is Individual Health Insurance?
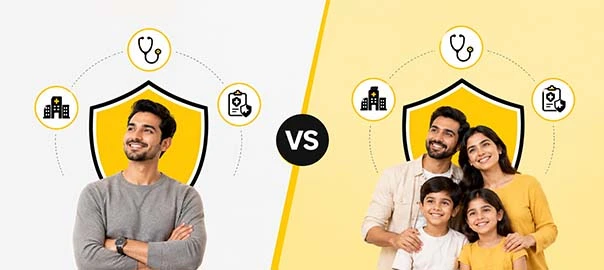
As the name indicates, individual health insurance refers to a plan that provides a separate sum insured for each person covered under the policy. Each person can use the entire sum insured to cover medical expenses arising from hospitalisation or treatment of other diseases covered under the policy, subject to the policy’s terms.
It won’t affect the coverage of other individuals. For example, if you purchase a ₹15 lakh individual health insurance policy for yourself, the entire ₹15 lakh sum can be utilised for your healthcare expenses. Your claim won’t reduce a separate sum insured held by another family member under their own individual policy.
This policy structure is particularly beneficial when family members have significantly different ages, health profiles, or expected healthcare needs. Consider an individual plan if you want customised coverage for each person, based on their unique healthcare needs and condition.
What is Family Floater Health Insurance?
Family floater insurance is the most common health insurance plan for Indian families. If you have a large family, comprising parents, spouse, children, etc., then you can cover everyone under the same family floater policy. In this case, every member insured under the policy shares a common pool for healthcare expenses.
For example, if you’ve purchased a ₹30 lakh policy for the entire family, everyone shares that same amount. If one member gets hospitalised or undergoes surgery costing ₹15 lakh, then only the remaining ₹15 lakh sum insured will be available for the rest of the family members.
In case the entire ₹30 lakh gets utilised for treatment of one member, you can avail restorative benefits to restore the original sum insured, subject to applicable terms and conditions. For large families, this policy makes maintenance easier.
Individual Health Insurance vs Family Floater: Key Differences
If you’re still unsure which option is better in the individual health insurance vs family floater debate, the following comparison table will help you make an informed decision.
| Basis of Differentiation | Individual Health Insurance Plans | Family Floater Health Insurance Plans |
|---|---|---|
| Coverage Sharing | Each insured person has a separate sum insured that they can use entirely towards their healthcare expenses. | All covered members draw from the same sum insured pool. |
| Impact of a Claim | A claim filed by one individual doesn’t impact others’ sum insured amount because each person has a separate sum insured assigned to their name. | A single large claim can reduce the common pool available to other family members. Restorative benefits can be used to restore the sum insured if a single claim exhausts the entire pool. |
| Ideal For | Recommended for families wherein each member has a widely different health profile, age group, and healthcare needs. | Ideal for families where members have broadly similar or moderate healthcare needs, and can reasonably share a common pool. |
| Premium | Purchasing separate individual plans for multiple members can lead to higher premiums. | Family floaters are usually economical because multiple members share a common pool. However, premiums can still be higher, depending on the member’s age, health profile, and other key factors. |
Family Floater Benefits You Should Know
Family floater insurance provides more than administrative convenience and coverage flexibility. We’ve shared key family floater benefits to help you decide whether it’s worth considering.
One Policy for Multiple Family Members
A family floater allows multiple eligible family members to be covered under a single health insurance policy. It saves you from the hassle of managing multiple separate policies.
Flexibility in Sum Insured
In a family floater plan, everyone shares a common pool. If you’ve taken a higher sum insured and a severe medical emergency arises, you can use the entire sum insured to cover necessary treatments, rather than arranging additional funds for hospitalisation and other treatment-related expenses.
Comparatively More Cost-Effective
Although premiums vary depending on several factors, family floaters are usually more economical than buying separate individual policies for every family member.
Scope to Accommodate Growing Family
If you’re a married couple whose current family floater plan includes you, your spouse, and your parents, you can later add your kids to the same policy as your family expands.
Coverage and Premium Comparison
The family floater vs individual health insurance comparison remains incomplete without analysing coverage and premiums. If you explore individual health insurance plans, you’ll understand how they assign a dedicated sum insured to each person. A family floater, on the other hand, provides one sum insured for the whole family.
Let’s understand it with an example. If a family of four takes a ₹20 lakh cover under an individual health insurance plan, then each person will have a separately selected sum insured. It can be ₹5 lakh each or any other sum distribution as agreed between the policyholder and insurer.
Now, if a person files a claim of ₹5 lakh from their sum insured, it won’t reduce the sum insured of the other members. But if a family floater is taken worth ₹20 lakh, the entire amount becomes a shared pool. If one member uses ₹12 lakh, the remaining ₹8 lakh becomes available to the rest of the family members, subject to the policy’s terms.
So, people who want fixed coverage for themselves should consider individual health insurance, while those comfortable with shared coverage can explore family floater insurance. Premiums also work differently.
Although family floaters are generally more cost-effective, they can also have higher premiums depending on the member’s age, health profile, and healthcare needs. You shouldn’t choose one between individual vs family floater plans based on lower premiums. Pick one that aligns with your healthcare requirements.
Who Should Choose an Individual Health Insurance Plan?
You should choose an individual health insurance plan if -
- Your family members have widely different healthcare needs
- You have older members with numerous pre-existing conditions
- You want dedicated coverage for yourself or other family members
Who Should Consider a Family Floater Plan?
Anyone can consider purchasing the best family health insurance if they want –
- Shared coverage for their family
- Economical health insurance without compromising on coverage
- Ease of maintenance
It’s ideal if your family shares a broadly similar health profile and can comfortably manage healthcare expenses with a shared pool.
Conclusion
Choosing the right type of health insurance plan is as important as purchasing one. If you’re currently exploring individual and family floater plans, then the insights shared in this blog can help you choose the right option.
Analyse your healthcare needs before choosing a plan. If you’re looking for dependable health insurance for yourself and your family, then explore the Shri Health Suraksha Insurance policy available at Shriram General Insurance.
FAQs
Which policy is better for receiving a dedicated sum insured for each member?
If you don’t want shared coverage, then individual health insurance plans are a better choice. They’ll provide a separate sum insured for each member.
Is a family floater plan cheaper than an individual health insurance plan?
Although family floaters are considered economical, they’re not always cheaper than individual health plans. Sometimes, they can be more expensive depending on the member’s age, pre-existing health conditions, and other factors.
What if a single claim exhausts the entire sum insured in a family floater plan?
In such cases, you can avail the policy’s restoration benefits. It will restore the entire sum insured, subject to the policy’s terms, so other family members remain protected during possible medical emergencies.
Can my parents be covered in a family floater plan?
Yes, you can cover your parents in a family floater plan. You can also include your spouse and children in the same plan for ease of management.
Who cannot be included in a family floater plan?
You cannot include extended family members, such as uncles, aunts, cousins, etc., in a family floater plan.

Save up-to 90% off on your Car Insurance
Related Posts
What Is Covered and Not Covered Under Health Insurance?
Posted on September 28,2026share


Copied
How to Determine the Ideal Health Insurance Coverage for Family Needs
Posted on September 17,2026share
Copied