What Is Covered and Not Covered Under Health Insurance
28 September,2026
Updated:28 September,2026
0 min read

share


Copied
 10
This blog lists the inclusions and exclusions common in health insurance coverage.
Having health insurance can ease your financial burden during medical emergencies, but it won’t cover every medical expense. Insurers have certain exclusions, applicable limits & sub-limits, waiting periods, etc., that influence coverage and claim amounts.
Not having clarity about your health insurance coverage can lead to unpleasant experiences during claim settlement. Hence, we’ve shared what’s usually covered and not covered in health insurance plans in this blog. It will help you prepare accordingly for potential medical emergencies.
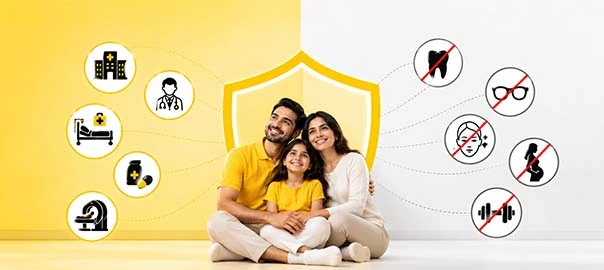
Understanding Health Insurance Coverage
Health insurance coverage refers to the medical expenses an insurer agrees to pay or reimburse under the terms of the policy.
Depending on the type of policy you’ve purchased, the coverage can span across in-patient hospitalisation, pre- and post-hospitalisation, ambulance charges, etc.
Every policy has its terms, exclusions, and waiting period, so ensure you read all the policy clauses for clarity about the policy’s coverage.
What Does Health Insurance Usually Cover
We’re sharing a health insurance coverage list that highlights what’s usually included in a policy’s coverage.
● Hospitalisation Expenses
If the policyholder or any member covered in the policy is admitted to a hospital for treatment of an eligible disease, the insurer will cover eligible hospitalisation expenses.
It includes expenses incurred towards room rent, ICU/ICCU, medicine & drugs, specialist fees, diagnostics, etc. However, be aware of the applicable limits for each hospitalisation expense. You’ll find it in the policy documents.
● Pre- & Post-Hospitalisation Expenses
One key health insurance benefit is coverage for eligible expenses incurred before and after hospitalisation. If a doctor prescribes certain diagnostic tests before surgery or recommends follow-up consultations after discharge, the policy commonly covers such expenses.
● AYUSH Treatment
Since many Indian citizens rely on alternative treatments, health insurance plans now cover eligible expenses for AYUSH treatment as well. However, you must receive the treatment in a certified AYUSH hospital on an inpatient hospitalisation basis.
● Ambulance Charges
Health insurance plans even cover ambulance charges. At Shriram General Insurance, we also cover air ambulance charges, subject to the policy’s terms and applicable limits.
Hospitalisation Expenses Covered Under Health Insurance
Here’s an expanded list of hospitalisation expenses that are generally covered under health insurance policies:
- Room rent
- ICU/ICCU charges
- Nursing expenses
- Fees paid to the surgeon, anaesthetist, specialist, medical practitioner, etc., provided they’re part of the hospital bill.
- Amount paid towards anaesthesia, blood, oxygen, operation theatre charges, etc.
- Diagnostic tests
- Medicines and drugs
- Ambulance charges
- Pre- & post-hospitalisation expenses
If you’ve purchased add-ons, such as consumables cover, the cost incurred for gloves, syringes, masks, bandages, and other consumables will also be part of the coverage.
Disclaimer: Every policy has a limit assigned to room rent, nursing, ICU, and other hospitalisation expenses. Hence, any expense incurred outside the limit must be paid by the policyholder. Read the policy’s terms and conditions thoroughly to avoid unrealistic claim expectations.
Health Insurance Benefits You Should Know
Health insurance policies do more than pay eligible hospital bills. Explore the following health insurance benefits to understand their relevance.
● Financial Protection Against Huge Medical Bills
A major illness, surgery, or accident can result in a substantial hospital bill. With health insurance, your savings remain protected. The insurer will cover all eligible expenses, while you’ll only have to cover the deductibles and other ineligible expenses.
● Cashless Treatment Facility
If you get treatment in a network hospital, the insurer will settle the hospital bill directly with the hospital. This cashless treatment facility can bring immense relief to the policyholder during medical emergencies.
You can focus more on the person admitted for treatment rather than struggling to arrange substantial funds for upfront payment during admission.
● Coverage Beyond Basic Hospitalisation
Health insurance coverage isn’t limited to expenses incurred during hospitalisation. You can also claim eligible expenses, such as diagnostic tests, medicines, consultation charges, etc., prescribed by a doctor before and after hospitalisation.
It can help you and those covered in the policy access quality healthcare services without being burdened by rising healthcare costs.
What is Not Covered Under Health Insurance? Common Exclusions
To have a hassle-free experience with health insurance claims, you must know what the insurer does and doesn’t cover. Treatment costs for the following are usually excluded from policy coverage:
- Pre-existing conditions (if the treatment is availed before the completion of the waiting period)
- Obesity/weight control
- Change of gender
- Cosmetic surgery
- Consequences arising from alcoholism, drugs, or substance abuse
- Unproven treatments
- Self-inflicted injuries
Many insurers also reserve the right to reject a claim if the treatment was necessitated by an injury caused by participation in adventure sports, such as skydiving, rafting, horse racing, or rock climbing.
Disclaimer: This is an illustrative list of common exclusions. Read your policy’s clauses and terms to review the full list of health insurance exclusions.
Understanding Waiting Periods and Policy Conditions
People planning to buy health insurance should know the waiting period their insurer follows. It’s the duration during which you cannot claim treatment expenses for illnesses specified in the policy.
Some illnesses have longer waiting periods than others. For example, hernia, piles, tonsillectomy, hydrocele, non-infective arthritis, etc., may have a waiting period of 24 months, while age-related osteoarthritis & osteoporosis might have a higher waiting period of up to 36 months.
You’ll find the full list of illnesses and their respective waiting periods in the policy documents, so be sure to read them thoroughly. It will help you determine when certain coverage benefits will become claimable. You should also be aware of other policy conditions that influence claims.
One crucial condition is that no treatments are covered within the first 30 days of the policy’s commencement. The only exception to this rule is when the hospitalisation is caused by an accident. Having clarity about waiting periods and policy conditions will ensure you clearly understand what’s covered and from when.
Health Insurance Claim: What Should You Know?
A health insurance claim can be viewed as a formal request to your insurer to pay eligible medical expenses covered by your policy. Claims work in two ways: cashless treatment and reimbursement. If you’re getting the treatment in a network hospital, the insurer will settle the approved bill directly with the hospital, instead of releasing the approved claim to your registered account.
A cashless claim can reduce mental, emotional, and financial pressure during medical emergencies. If you had to avail treatment in a non-network hospital for unavoidable reasons, you’ll have to pay all expenses from your own pocket.
Once the patient is discharged, you can raise a reimbursement claim request with all supporting documents. Upon approval, the insurer will transfer the claim amount to your registered account. If you have specific questions about the claim settlement process, you can contact the insurer’s customer support team for clarification.
Conclusion
Purchasing health insurance has become a necessity, but you won’t be able to avail yourself of its full benefits if you’re unaware of what the policy covers and excludes. Although no two policies are the same, we’ve shared what’s commonly covered and not covered in health insurance plans for your reference.
You can further read the policy’s full terms and conditions for clarity. If you’re looking for a dependable policy to meet all your healthcare needs, check the Shri Health Suraksha Insurance plan available at Shriram General Insurance.
FAQs
1. Are all hospital expenses covered under health insurance policies?
No, not all hospital expenses are covered. Even eligible expenses for room rent, ICU, and certain treatments like cataract surgery are subject to limits.
2. How long is the waiting period for pre-existing diseases?
There is no fixed waiting period for all pre-existing diseases. You must read the policy’s waiting period clause to identify the waiting period for different illnesses or health conditions.
3. Can I claim ambulance charges?
Yes, ambulance charges are covered under health insurance plans. Check whether there’s an applicable limit on ambulance charges or whether the full charges are covered. You’ll find this detail in the policy’s documents.
4. What is generally covered in health insurance plans?
Usually, health insurance plans cover hospitalisation expenses, including room rent, diagnostic tests, ICU charges, nursing costs, etc. Even pre- and post-hospitalisation charges are covered to minimise the financial burden of treatment on policyholders.
5. Why should I purchase a health insurance plan?
You should consider purchasing it if you want a financial safety net for medical emergencies. It will help you and your family members access reliable healthcare services without worrying about the high medical costs.