Health Insurance vs Critical Illness Insurance: What the Difference?
13 October,2026
Updated:13 October,2026
0 min read

share


Copied
 30
This critical illness vs health insurance guide shares key differences between the two, so you can choose the policy that best fits your needs.
With medical inflation averaging 10% to 15% annually in India, it’s wiser to start building a financial safety net early to handle possible medical emergencies that may arise in the future. If you’re exploring insurance options to cover all your healthcare needs, you may come across two popular options - critical illness insurance and regular health insurance policies.
Although both these policies provide financial protection during medical emergencies, they work differently. They even cover different needs and release benefits differently. If you’re unsure which policy is right for you, this health insurance vs critical illness guide can help you choose confidently.
What is Health Insurance?
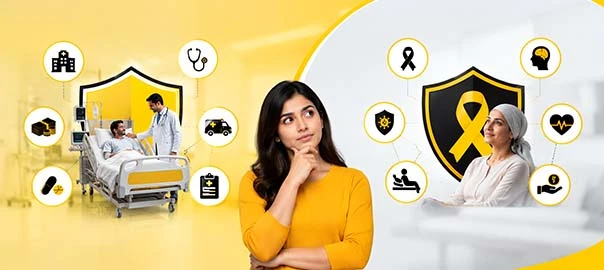
Health insurance is a financial protection product designed to help policyholders manage eligible medical expenses arising from illness, injury, or hospitalisation. It can significantly reduce policyholders’ financial burden during medical emergencies. Depending on the policy, health insurance coverage usually includes –
- Hospitalisation expenses
- Pre- and post-hospitalisation expenses
- Daycare procedures
- Ambulance charges
- Cost of consultation, diagnostic tests, medicines, etc.
Not every medical expense is covered under the policy, and even eligible expenses have a fixed higher limit. So, always read the policy’s terms carefully to understand what’s covered and what’s excluded.
What is Critical Illness Insurance?
Critical illness insurance is generally a benefit-based health insurance product. It pays a pre-defined lump sum amount to the policyholder upon the qualifying diagnosis of an illness specified in the policy.
Unlike indemnity-based health insurance plans, critical illness cover releases a lump sum amount to the policyholder upon the diagnosis of a specified illness, not actual treatment expenses. The policyholder can use the entire lump sum payment for treatment, lifestyle expenses, or any other purpose they prefer.
Health Insurance vs Critical Illness Insurance: Key Differences
The following comparison table on health insurance vs critical illness insurance will help you understand how both policies differ at varying levels.
| Basis of Differentiation | Health Insurance | Critical Illness Insurance |
|---|---|---|
| Designed To | Cover eligible medical expenses arising from injury, illness, or hospitalisation. | Provide a lump sum payment once the policyholder is diagnosed with an illness specified in the policy, subject to approval and policy terms. |
| Coverage Scope | Covers a broader range of injuries, illnesses, and eligible treatments, provided they’re not on the exclusion list and the waiting period has passed. | Covers only critical illnesses listed in the policy, subject to definitions and conditions specified by the insurer. |
| Payout | The payout is either in the form of cashless treatment (insurer settles the approved bill directly with the network hospital) or reimbursement (you pay the medical expenses upfront, and later raise claim for reimbursement). | A lump sum amount is paid upon illness diagnosis; you can use it for treatment, lifestyle maintenance, or any other purpose. |
| Ideal For | Individuals and families seeking financial protection against healthcare and hospitalisation costs. | Individuals seeking financial support for specific chronic illnesses. |
| Limitation | The applicable waiting period, exclusions, sub-limits, and deductibles can affect your claim amount. | Only specified illnesses are covered, and claims depend on policy definitions, survival periods, and other conditions as applicable. |
Difference in Coverage and Benefits
When analysing critical illness vs health insurance cover, explore the type of financial protection each policy provides. With a regular health insurance plan, the coverage typically includes eligible medical costs, including -
- Hospitalisation
- Surgery
- Specialist consultation
- Medicine
- Diagnostic tests
Critical illness insurance provides a widely different type of financial protection. It pays a pre-defined lump sum when the policyholder is diagnosed with a covered illness, meeting all the policy terms. The biggest benefit of critical illness cover is that it provides financial flexibility to manage the wider impact of a serious illness.
Health insurance coverage will help you manage the direct cost of treatment and hospitalisation, while critical illness cover will provide a lump sum that can be used to cover treatment costs, income loss due to a prolonged recovery period, or manage household expenses.
How Does the Claim Process Differ?
The claim process remains a crucial factor in the health vs critical illness analysis. Both policies have different claim processes because an insurer examines each claim through a different lens. In health insurance, claims are settled in one of two ways: cashless treatment or reimbursement.
You can avail cashless treatment only if you seek hospitalisation in a network hospital. You’ll need to approach the Third-Party Administrator (TPA) at a network hospital to submit a cashless treatment request to the insurer. Once approved, the insurer will directly settle the eligible bill with the network hospital.
You may still have to pay ineligible medical expenses and deductibles out of pocket. For reimbursement claims, you’ll have to pay all medical expenses upfront and later raise a claim request with all supporting bills and documents. Upon inspection and approval, the insurer will release the claim amount.
If you have a critical illness cover, you will have to submit medical reports and other diagnosis-related documents to establish that the covered illness meets the policy’s definition. The insurer will then assess the claim against the policy conditions, including applicable survival periods. If approved, the specified lump sum amount will be paid according to the policy’s terms.
Can You Have Both Health and Critical Illness Insurance?
Some people view health and critical illness insurance as competing policies, but they’re complementary. If you want to protect yourself from the immediate and long-term financial implications of a serious illness or major hospitalisation, you can buy both health and critical illness plans for broader coverage.
The regular health insurance will take care of eligible hospitalisation expenses, including room rent, ICU, surgery, diagnostic tests, etc., subject to applicable limits and approval.
However, critical illness insurance will give you a lump sum amount. The policyholder can use it to cover additional treatment expenses, make up for the income loss during recovery period, or any other purpose the policyholder deems fit.
Which Insurance is Better for Your Needs?
You can identify the ‘better’ option only after understanding your precise needs. Health insurance might be a considerably better option if your priority is financial protection against hospitalisation and other eligible medical expenses. It’s particularly relevant for individuals and families who want broader coverage for medical expenses.
Critical illness insurance can be an ideal choice if you already have health insurance, but want additional protection against a specific critical illness. You might need it for -
Managing the High Cost of Treatment
Treatment for critical illnesses usually involves substantial medical expenses, including hospitalisation, surgery, specialised treatment, or long-term care. The payout from this policy can help you cover the higher cost of treatment.
Financial Support When Illness Affects Your Ability to Earn
A serious illness, such as cancer, may require prolonged treatment and recovery, potentially affecting your ability to work and earn an income during this period. The lump sum payout from a critical illness plan can help you manage household expenses and other financial commitments during this phase.
Greater Flexibility in Using the Lump Sum Amount
Unlike a regular health insurance plan, where the claim or reimbursement is tied to eligible medical expenses specified in a hospital bill, a critical illness plan pays the pre-agreed lump sum upon the diagnosis of a critical illness covered in the policy.
You have complete authority to decide where and how this amount will be used. The insurer won’t ask any questions as to how the claim amount will be used.
Managing Outstanding Loans & Other Financial Commitments
A critical illness can create financial pressure, especially if the diagnosis has affected your earning ability. If you had to stop your work for treatment and recovery, managing existing financial commitments can become challenging.
If you have an ongoing home loan, personal loan, or other significant liabilities that require timely payments, then you can use the lump sum received from the critical illness plan to tackle any outstanding debt while focusing on your recovery.
Before choosing a policy, assess your existing healthcare coverage, financial responsibilities, health risks, and other key factors. If needed, you can purchase both for enhanced financial protection.
Conclusion
Both health insurance and critical illness insurance provide financial protection during medical emergencies. However, their structure, claim payouts, benefits, and features differ significantly.
We created this health insurance vs critical illness insurance guide to help you better understand each policy. This clarity can help you choose the right policy aligning with your healthcare needs and desired financial protection. Once you’ve decided which type of policy you need, you can explore our Shri Health Suraksha Insurance policy and Shri Criti Care Insurance policy.
FAQs
How is a regular health insurance plan different from a critical illness insurance plan?
A regular health insurance plan covers a wide range of medical expenses arising from hospitalisation, treatment, or injury. The claims are paid based on actual expenses incurred during treatment/hospitalisation, subject to policy’s terms.
With critical illness insurance, you receive a lump sum amount upon illness diagnosis. The illness must be covered in the policy and meet all approval terms laid down by the insurer.
Can a person purchase both health and critical illness insurance plans?
Yes, people can purchase both. In fact, these two policies can provide complementary coverage for enhanced protection.
Can I use the claim amount from critical illness insurance to cover household expenses?
Yes, you can. Critical illness insurance provides greater financial flexibility. Once the claim is approved, you’ll receive a lump sum payment. You can choose to use it for any purpose.
Is health insurance better than critical illness cover?
There’s no universally better option, as both policies are designed for entirely different purposes. You can choose health insurance if you want financial protection from healthcare expenses. Critical illness cover is ideal if you want financial support during a long treatment or recovery period due to income loss.
Do health insurance plans cover all medical expenses?
While health insurance coverage includes a wide range of treatments, illnesses (after the specified waiting period), and injuries, it doesn’t cover every type of medical expense.
For example, expenses related to bandages, gloves, masks, etc., are usually not covered unless you’ve purchased a consumables add-on. Even other eligible expenses have applicable sub-limits, so read the full policy terms to understand what’s covered.

Save up-to 90% off on your Car Insurance
Related Posts
What Is Covered and Not Covered Under Health Insurance?
Posted on September 28,2026share


Copied
How to Determine the Ideal Health Insurance Coverage for Family Needs
Posted on September 17,2026share
Copied